BuyingLake Wylie, SCNo. 114
Buying Waterfront Property in Lake Wylie, SC
A due diligence guide for South Carolina–side lake homes: access types, shoreline and depth, Duke Energy dock permits, flood insurance, taxes and financing.

By Ally BohananPublished 5 min read
In this article
- What kind of water access are you buying?
- How do you judge the shoreline and depth?
- What does Duke Energy control?
- How should you inspect the dock?
- What will insurance cost?
- How are property taxes different in South Carolina?
- Does the lake change through the year?
- How does financing work for waterfront homes?
- Waterfront buyer checklist
- Frequently asked questions
The short answer
Buying on Lake Wylie means checking more than the house. Confirm the type of water access, the water depth at the dock, and that any dock is permitted by Duke Energy. Check the FEMA flood zone and get insurance quotes early. Then line up a lender who knows waterfront appraisals and, often, jumbo loans.
Key takeaways
- "Lake property" can mean direct frontage, deeded access, a community dock or just a view; confirm which in the deed.
- Duke Energy manages Lake Wylie and permits docks and shoreline work, so verify any existing dock's permit.
- Ask about water depth at the dock when lake levels are lower, and inspect the dock separately from the house.
- Flood zone, flood insurance and higher homeowners premiums belong in your budget from the start.
- On the South Carolina side, owner-occupants can apply for the lower 4% legal residence assessment ratio on property taxes.
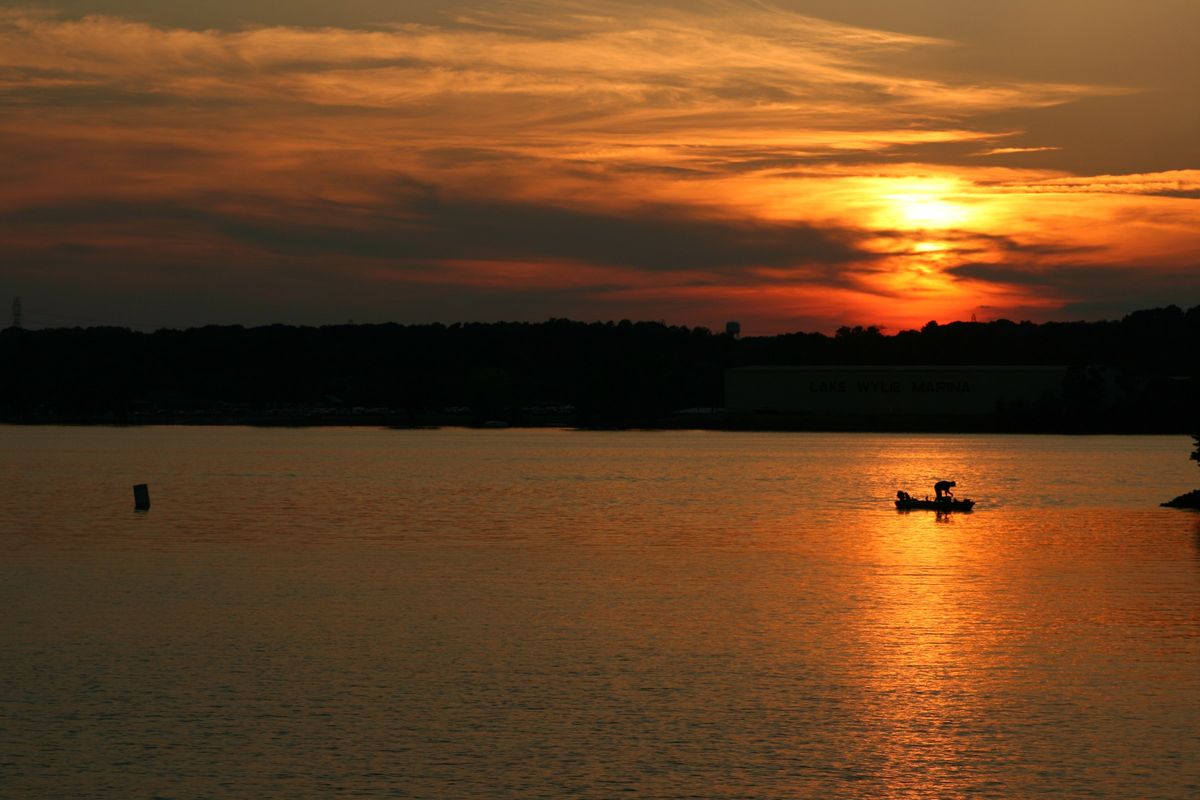
Lake Wylie is the waterfront market closest to Charlotte. It sits on the Catawba River along the North Carolina–South Carolina line, bordered by Gaston and Mecklenburg counties in North Carolina and York County in South Carolina. According to the SC Department of Natural Resources, the lake covers about 13,400 acres with roughly 325 miles of shoreline, and it's owned and managed by Duke Energy.
A waterfront purchase has more moving parts than a typical home sale. You're buying a house, a shoreline and often a dock, each with its own rules and risks. This guide focuses on the South Carolina side of the lake. For lifestyle and neighborhood information, see our Lake Wylie homebuyer guide.
What kind of water access are you buying?
| Type | What you get | What to check |
|---|---|---|
| Direct lakefront | Your lot meets the shoreline; you may have or add a private dock | Survey, Duke Energy dock permit, depth, shoreline condition |
| Deeded access | A recorded right to reach the water by path, easement or shared launch | The exact wording in the deed and any shared-maintenance terms |
| Community amenities | Shared docks, slips, swim areas or a clubhouse | HOA rules, slip availability and waiting lists, dues |
| Water view | A view of the lake, no private access | Whether the view could be blocked; don't pay a waterfront premium |
Listings use "lake home" loosely. Read the deed and plat, not just the listing description.
How do you judge the shoreline and depth?
Two homes of the same size can differ a lot in value because of the shoreline:
- Depth at the dock: if you'll keep a boat, ask what the depth is when the lake is lower than full pond. Duke Energy publishes current levels and explains how they're managed on its lake level basics page.
- Shoreline type: rocky or stabilized banks are usually more stable. Soft banks can erode and may need riprap or other stabilization, which requires permitting.
- Cove or open water: coves are calmer for swimming and paddling. Open water has bigger views but more wave action on docks.
- Usable frontage: a wide, gentle slope to the water is worth more than a narrow strip at the tip of a lot. Walk the whole waterfront.
What does Duke Energy control?
Duke Energy operates the Wylie Hydroelectric Station and manages lake levels. It also reviews docks, boat lifts and most shoreline changes through its shoreline permitting program, in addition to any York County or Gaston County building permits.
Before you commit, confirm:
- Is the existing dock permitted, and does its current size and layout match the permit?
- Are there any open violations or unresolved permit issues?
- If you plan to add or expand a dock, what will the rules allow on this lot?
Unpermitted additions can become your problem after closing.
How should you inspect the dock?
Hire a dock or marine inspector in addition to your home inspector. Ask them to check:
- Decking and framing: composite decking lasts longer; older treated wood needs more upkeep.
- Pilings and floats: look for rot, damage or movement at the waterline.
- Electrical: dock power for lights, lifts and shore power needs to meet code for wet locations. Ask for inspection records.
- Boat lift: condition, capacity and motor operation.
What will insurance cost?
Standard homeowners policies don't cover flood damage. Look up the property on FEMA's Flood Map Service Center. If it's in a Special Flood Hazard Area and you have a federally backed mortgage, flood insurance is required. Even outside those zones, many lakefront owners carry it.
- Get quotes through the National Flood Insurance Program and from private flood insurers.
- Ask the seller for their current flood policy and any elevation certificate.
- Expect homeowners premiums for waterfront homes to differ from inland homes, and get quotes before your due diligence period ends.
How are property taxes different in South Carolina?
South Carolina assesses an owner-occupied legal residence at 4% of its value, compared with 6% for second homes and rentals. You have to apply with the county to get the 4% rate. If the lake home will be your primary residence, ask the York County assessor's office about the application, and confirm the current tax bill on any property you're considering. The SC Department of Revenue explains property tax basics.
On the North Carolina side, homes are taxed at assessed value set by each county's revaluation. Compare the actual tax bills on homes you're weighing on each side of the lake.
Does the lake change through the year?
- Summer: peak boating season. Weekend traffic picks up, especially on open water.
- Fall and winter: quieter, and levels may run lower, which can affect shallow docks.
- Spring: activity picks back up as the weather warms.
If you're buying a second home, think honestly about how many weekends you'll use it.
How does financing work for waterfront homes?
- Appraisals: waterfront comparables are limited, so appraisals can be harder. Ask whether your lender uses appraisers familiar with lake properties.
- Jumbo loans: many lakefront homes are priced above conforming loan limits. Requirements for down payment, credit and reserves vary by lender.
- Second homes: terms differ from a primary residence. Tell your lender up front how you'll use the home.
- Insurance and qualifying: required flood insurance is part of your monthly payment and affects your debt-to-income ratio.
Our preferred lender page and mortgage calculator can help you plan.
Waterfront buyer checklist
- Confirm the access type in the deed and plat.
- Verify the dock's Duke Energy permit and compare it to what's built.
- Ask about depth at the dock in lower-water months.
- Order a home inspection and a separate dock inspection.
- Check the FEMA flood zone and get flood and homeowners quotes.
- Review HOA documents for dock, slip and shoreline rules.
- Confirm property taxes and your eligibility for the 4% rate.
- Line up financing that fits waterfront and, if needed, jumbo loans.
Ally also runs Bohanan Construction, which builds custom homes in Gastonia, so she looks at lake homes, renovations and additions with a builder's eye. Learn more about Bohanan Construction.
Ready to tour? Talk With a Buyer's Agent, and we'll start with the parts of the lake that fit your plans. More on the area is on our Lake Wylie community page.
Sources cited in this article: dnr.sc.gov, duke-energy.com, FEMA Flood Map Service Center, floodsmart.gov, dor.sc.gov. Figures are as reported by those sources at the time of writing.