BuyingMount Holly, NCNo. 136
First-Time Buyer Agent Tips for Mount Holly, NC
Ten practical tips for first-time buyers in Mount Holly, from pre-approval and buyer agreements to inspecting older in-town homes and writing a strong offer.

By Ally BohananPublished 3 min read
In this article
- 1. Why should you get pre-approved first?
- 2. What should your monthly payment include?
- 3. What should you know about buyer agreements?
- 4. Why use your own buyer's agent?
- 5. How do you get to know Mount Holly's neighborhoods?
- 6. Do older homes need special inspections?
- 7. What about flood zones near the river?
- 8. How does the North Carolina contract protect you?
- 9. How do you write a strong offer?
- 10. Who should be on your team?
- What's a typical timeline?
- Frequently asked questions
The short answer
First-time buyers in Mount Holly should get pre-approved before touring, sign a clear written buyer agreement with their own agent, and compare recent sales before offering. Inspect older in-town homes carefully, check flood zones near the Catawba River, and set a due diligence period long enough for inspections, insurance quotes and HOA review.
Key takeaways
- Pre-approval, not pre-qualification, is what makes your offer credible to Mount Holly sellers.
- Since 2024, you'll sign a written buyer agreement before touring; read how your agent is paid and for how long.
- Older homes near downtown need careful inspection; newer subdivisions need HOA review.
- Homes near the Catawba River or creeks should get a flood zone check and an insurance quote early.
- Your due diligence period is your main protection under North Carolina's standard contract, so plan it carefully.
Buying your first home is exciting and a little intimidating. Mount Holly makes a good place to start: a small downtown, the Catawba River on its doorstep, and a short drive across the river to Charlotte. It also has its own quirks, from older in-town homes to fast-growing subdivisions and river-adjacent lots. These ten tips will help you buy with confidence.
1. Why should you get pre-approved first?
Pre-approval means a lender has reviewed your income, credit, debts and assets and can say how much you can borrow. Pre-qualification is a rough estimate based on what you report. Sellers take pre-approved offers more seriously, and knowing your number keeps you from falling for homes outside your budget. Start with our preferred lender.
2. What should your monthly payment include?
Your real payment is principal and interest plus property taxes, homeowners insurance, mortgage insurance if your down payment is under 20%, and any HOA dues. Run scenarios in our mortgage calculator, then set a payment you're comfortable with, not just the maximum you qualify for.
3. What should you know about buyer agreements?
Since August 2024, buyers working with an agent sign a written agreement before touring homes. It spells out what services you'll get, how your agent will be paid, and for how long. Read it, ask questions and negotiate if needed. In North Carolina you'll also receive the Real Estate Commission's "Working With Real Estate Agents" disclosure, which explains agency relationships.
4. Why use your own buyer's agent?
The listing agent's job is to get the best result for the seller. Your buyer's agent advises you on price, flags concerns and negotiates for you, even if that means recommending you walk away. Learn more on our buyer agent services page.
5. How do you get to know Mount Holly's neighborhoods?
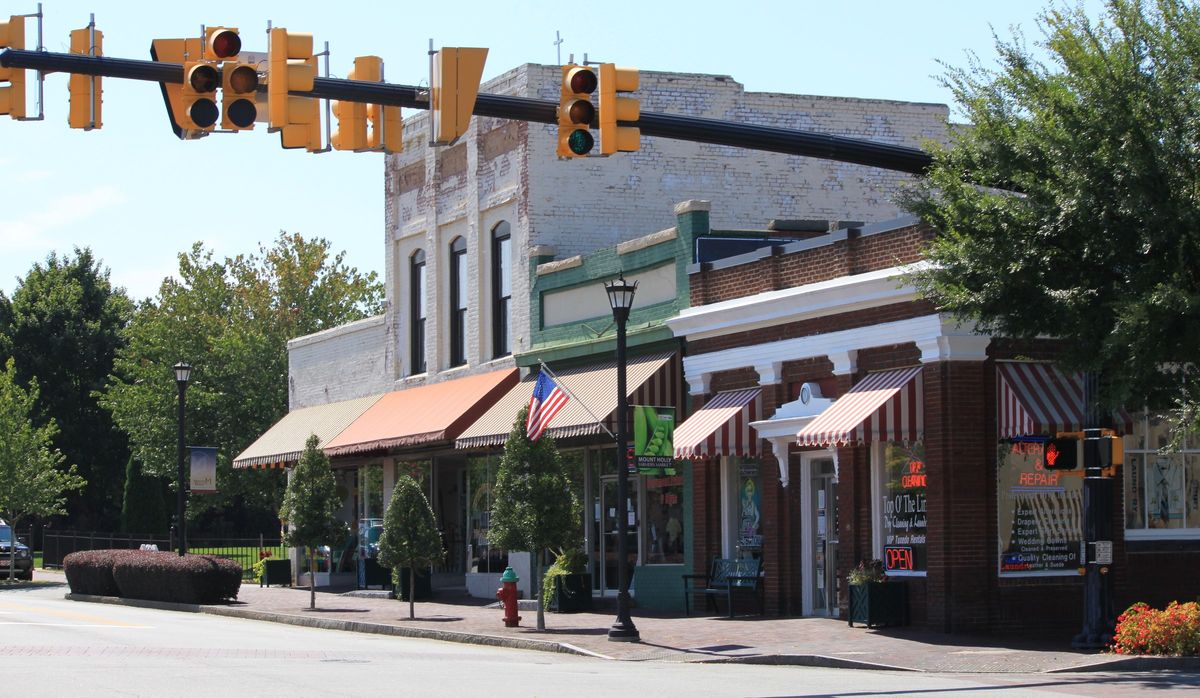
Mount Holly has a mix of older homes near the Main Street downtown, established neighborhoods and newer subdivisions on the edges of town. Spend time there before you commit:
- Drive your commute at rush hour, including NC 27 and the routes to I-85.
- Visit downtown on a weekday evening and a Saturday.
- Walk the riverfront parks and greenway areas.
- Check how far you are from groceries, schools and Mountain Island Lake or the U.S. National Whitewater Center if you'll use them.
Our Mount Holly guide covers the town in more detail.
6. Do older homes need special inspections?
Charming older homes can hide aging wiring, plumbing, roofs and crawl space moisture. Always get a full home inspection, and consider a sewer scope, a roofing specialist or an electrician if the inspector recommends one. New construction deserves an independent inspection too.
7. What about flood zones near the river?
Some Mount Holly properties sit near the Catawba River or creeks. Check the address on FEMA's Flood Map Service Center and get a homeowners and flood insurance quote during due diligence. Insurance costs can change your monthly payment.
8. How does the North Carolina contract protect you?
North Carolina's standard contract includes a due diligence period, a window to inspect, get insurance quotes, review HOA documents and finalize your loan. You pay a due diligence fee directly to the seller and an earnest money deposit held in trust. If you terminate before the period ends, you generally lose the due diligence fee but get your earnest money back. Choose a period long enough to do everything.
| During due diligence | Why |
|---|---|
| Home inspection and any specialist follow-ups | Find repair needs |
| Appraisal | Confirm value for the lender |
| Insurance quotes, including flood if relevant | Confirm your real payment |
| HOA documents and rules | Know fees and restrictions |
| Survey (optional but recommended) | Confirm boundaries |
9. How do you write a strong offer?
Ask your agent for recent comparable sales before you offer. A strong offer balances price with terms: a solid due diligence fee and earnest money, a reasonable timeline and a clean pre-approval. In multiple-offer situations, read our multiple-offer strategy guide for Mount Holly.
10. Who should be on your team?
- A buyer's agent who knows Mount Holly.
- A lender who explains your options, including NC Housing Finance Agency programs if you qualify.
- A licensed home inspector.
- An insurance agent.
- A closing attorney, since North Carolina closings are handled by attorneys.
What's a typical timeline?
Once you're pre-approved and know where you want to live, finding a home can take anywhere from a few weeks to a few months. From contract to closing, many financed purchases take about a month or a bit more, depending on the lender, appraisal and due diligence period.
Ready to start your search? Talk With a Buyer's Agent and we'll walk you through every step in Mount Holly.
Sources cited in this article: FEMA Flood Map Service Center, NC Housing Finance Agency. Figures are as reported by those sources at the time of writing.